by onchop.co.uk | Oct 28, 2026 | Good to Know
How to Pay Off Debt Faster : Snowball vs Avalanche Explained
Credit cards, overdrafts, a car loan, buy now pay later, a catalogue account: debt has a way of piling up quietly until the monthly repayments take a big bite out of your income. If that sounds familiar, you’re far from alone.
The good news is that with a clear plan, you can pay it off faster than you think. This guide walks you through the two most popular methods, the snowball and the avalanche, and how to choose between them.
Step 1: Get the full picture
You can’t beat what you can’t see. List every debt you have, with:
- who you owe;
- the balance;
- the interest rate (APR);
- the minimum monthly payment.
Check your credit report too, through one of the main credit reference agencies, to make sure nothing is missing.
Step 2: Deal with priority debts first
Not all debts are equal. Priority debts are those where falling behind can have serious consequences, such as losing your home, having your energy cut off or facing court action:
- rent or mortgage arrears;
- council tax;
- gas and electricity;
- court fines;
- income tax or VAT owed to HMRC;
- child maintenance.
These come before credit cards and loans, even if the interest rate is lower. If you’re behind on any of them, get free debt advice straight away (see below).
Step 3: Always pay the minimums
Keep paying at least the minimum on every debt to avoid fees, extra interest and damage to your credit file. Then put every spare pound towards one debt at a time. Which one? That’s where the two methods differ.
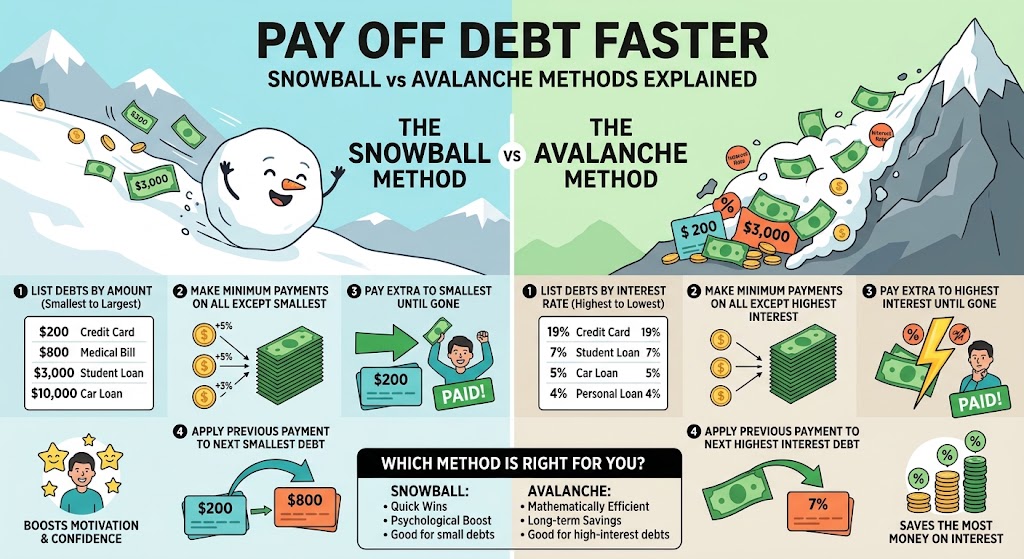
The snowball method
You pay off your debts from the smallest balance to the largest, regardless of interest rate.
- Pay the minimum on everything.
- Put all your extra money towards the smallest debt.
- When it’s cleared, add its payment to the next smallest.
- Repeat until you’re debt-free.
Why it works: quick wins. Clearing a debt completely in a few months is motivating, and that motivation keeps many people going.
The avalanche method
You pay off your debts from the highest interest rate to the lowest.
- Pay the minimum on everything.
- Put all your extra money towards the debt with the highest APR.
- When it’s cleared, move on to the next highest rate.
Why it works: mathematically, it’s the cheapest option. You pay less interest overall and usually finish sooner.
A worked example
Imagine you have £200 a month to put towards these debts, on top of minimum payments:
| Debt | Balance | APR |
|---|
| Store card | £600 | 29% |
| Credit card | £3,000 | 24% |
| Personal loan | £5,000 | 9% |
- Snowball: you clear the £600 store card first, then the credit card, then the loan. It happens to match the avalanche order here because the smallest debt also has the highest rate.
- But if the store card were at 15% and the credit card at 29%, the avalanche method would target the credit card first and save you more in interest, while the snowball would still start with the store card for the quick win.
Which to choose? If you need motivation, choose the snowball. If you’re disciplined and want to pay the least interest, choose the avalanche. The best method is the one you’ll stick to.
The faster you pay, the less interest you pay. A few ideas:
- Build a simple budget to see where your money goes each month.
- Cut or pause subscriptions you don’t use.
- Switch bills when contracts end: broadband, mobile, insurance, energy tariffs.
- Sell things you no longer need.
- Use a side hustle and put every penny it earns towards your debt.
- Direct windfalls (pay rises, tax refunds, bonuses) to your target debt.
- Check what you’re entitled to: benefits, discounts and council tax reductions you may be missing.
Should you keep a small emergency fund?
Yes. Without any savings, one unexpected bill can push you back onto your credit card. Many people keep a starter fund of around £1,000 while paying off debt, then build it up once the expensive debts are gone.
Balance transfers and consolidation loans
These can help, but only if used carefully.
Balance transfer credit cards
You move credit card debt to a new card with a low or 0% introductory rate for a set period. This can save a lot of interest, as long as you:
- check the transfer fee;
- pay off as much as possible before the promotional period ends;
- don’t build up new spending on the old card.
Debt consolidation loans
You take out one loan to pay off several debts, ideally at a lower interest rate. It simplifies things, but check the total cost over the full term: a longer loan can mean paying more overall, even at a lower rate.
Never consolidate unsecured debts into a loan secured on your home without independent advice: it puts your home at risk.
Free debt help in the UK
If your debts feel unmanageable, you’re behind on priority bills, or you’re borrowing to pay other debts, get free, confidential advice. Reputable free services include:
- StepChange Debt Charity
- National Debtline
- Citizens Advice
- MoneyHelper (government-backed)
They can help you create a budget, negotiate with creditors and explain formal options if needed. Be wary of companies that charge fees for debt solutions you could get free.
Mistakes to avoid
- Ignoring letters from creditors: contact them early, as most will work with you.
- Paying only the minimum forever: on credit cards, it can take many years to clear the balance.
- Borrowing more to pay debts without a plan.
- Closing paid-off accounts immediately without thinking about your credit file (this can affect your credit utilisation).
- Giving up after a setback: one missed month doesn’t cancel your progress.
Frequently asked questions
Should I pay off debt or save first?
Keep a small emergency fund, then focus on high-interest debt. Paying off a credit card at a high APR is usually a better “return” than most savings accounts.
Will paying off debt improve my credit score?
Reducing balances and paying on time generally helps your credit file over time.
How long will it take to become debt-free?
It depends on your balances, interest rates and how much extra you can pay each month. Listing your debts and using a free debt calculator gives you a realistic timeline, which is a great motivator.
Final thoughts
Paying off debt starts with facing the numbers. List every debt, deal with priority debts first, keep up the minimums, and then choose your method: the snowball for motivation, the avalanche to pay the least interest. If it all feels too much, free help is available, and asking for it is a smart move, not a failure.
This article is general information, not financial advice. If you’re struggling with debt, contact a free debt advice service.
by onchop.co.uk | Oct 27, 2026 | Good to Know
Emergency Fund UK
The boiler breaks in January. The car fails its MOT. Your hours are cut, or you lose your job. Life has a habit of sending expensive surprises at the worst possible moment.
An emergency fund is what stands between those surprises and a credit card bill you’ll be paying off for months. It’s the foundation of any healthy financial plan, and it should come before investing.
Why an emergency fund matters
- It stops small problems becoming debt. Without savings, an unexpected £600 bill often ends up on a credit card or an overdraft, with interest.
- It gives you choices. A cushion means you can leave a bad job, handle a gap between contracts, or take time to find the right next step.
- It protects your investments. With cash set aside, you won’t be forced to sell investments at a bad time to cover an emergency.
- It reduces stress. Knowing you can cope with a surprise makes a real difference to everyday wellbeing.
How much do you need?
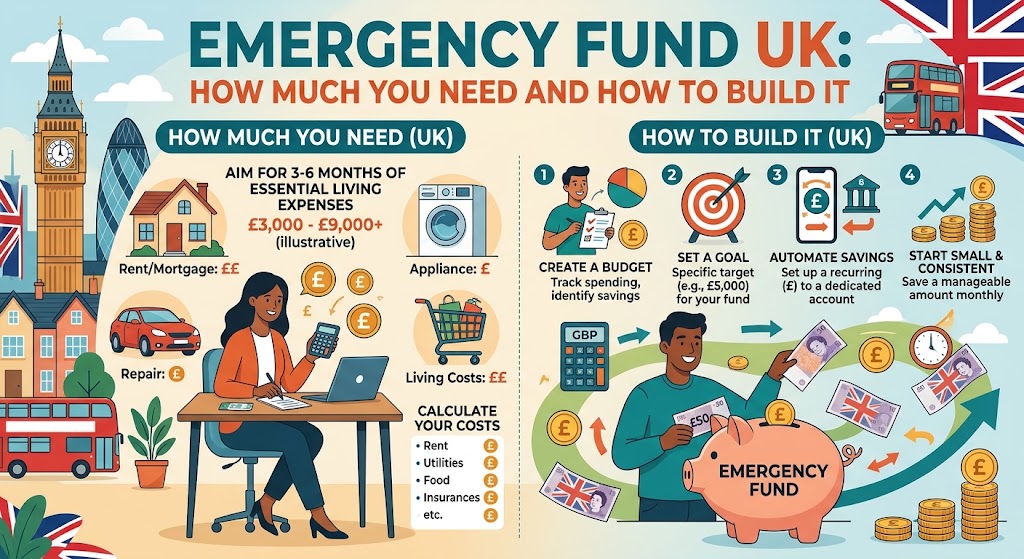
The common guideline is three to six months of essential spending. Not three to six months of salary: just what you need to cover the basics.
Calculate your essential monthly spending
Add up what you’d absolutely have to pay if your income stopped:
- rent or mortgage;
- council tax;
- energy, water, broadband and phone;
- food shopping;
- transport;
- insurance;
- minimum debt repayments;
- childcare and other essentials.
Leave out the nice-to-haves like takeaways, subscriptions and holidays.
Then adjust to your situation
| Your situation | Suggested target |
|---|
| Stable job, no dependants, renting | Around 3 months |
| Homeowner, or family with children | 4 to 6 months |
| Single income household | 6 months |
| Self-employed or irregular income | 6 months or more |
| Job in an unstable sector | 6 months or more |
Example: if your essential spending is £1,800 a month, a three-month fund is £5,400 and a six-month fund is £10,800.
If that feels impossible right now, don’t worry. Start with a smaller first goal: £1,000, or one month of essentials. That alone covers most everyday emergencies.
Where to keep your emergency fund
Your emergency fund needs to be safe, easy to access and ideally earning some interest. That rules out investments (which can fall in value right when you need them) and your everyday current account (where it’s too easy to spend).
| Option | Pros | Watch out for |
|---|
| Easy-access savings account | Instant or next-day access, simple | Rates vary, so compare regularly |
| Easy-access Cash ISA | Interest is tax-free | Check withdrawal rules and whether it’s a flexible ISA |
| Premium Bonds | Prizes are tax-free, capital-backed by the Treasury | No guaranteed return |
| Notice or fixed-term accounts | Higher rates | Not ideal for the whole fund, as access is restricted |
Check that your provider is covered by the Financial Services Compensation Scheme (FSCS), which protects eligible deposits up to a set limit per person, per banking licence.
A practical tip: keep your emergency fund at a different bank from your current account. It’s still easy to reach in a real emergency, but out of sight day to day.
Do you need to pay tax on the interest?
Most basic-rate taxpayers have a Personal Savings Allowance that lets them earn some savings interest tax-free. A Cash ISA keeps all interest tax-free regardless. If your emergency fund is large, a Cash ISA can be worth considering.
How to build your emergency fund
1. Set a first milestone
Start with £500 or £1,000, then one month of essentials, then three months. Small wins keep you motivated.
2. Pay yourself first
Set up a standing order to your savings account for the day after payday. Even £25 or £50 a month builds momentum.
3. Find the money
- Cancel subscriptions you don’t use.
- Switch broadband, mobile and insurance when contracts end.
- Sell things you no longer need.
- Put a side hustle’s earnings straight into savings.
4. Save windfalls
Pay rises, tax refunds, bonuses, birthday money: put at least half straight into your fund until you reach your target.
5. Use round-ups
Many banking apps can round up your card purchases to the nearest pound and save the difference automatically.
What counts as an emergency?
Yes:
- job loss or a sudden drop in income;
- urgent home repairs (boiler, leak, broken lock);
- essential car repairs if you need the car for work;
- unexpected medical, dental or vet costs;
- emergency travel for family reasons.
No:
- holidays, Christmas or birthdays (save for these separately);
- a sale on something you want;
- planned expenses you knew were coming.
After using your fund, make rebuilding it your first priority.
Emergency fund or paying off debt first?
A balanced approach works for most people:
- Build a starter fund of around £1,000.
- Pay off high-interest debts, such as credit cards and overdrafts.
- Then build your fund up to three to six months.
This way, a surprise bill doesn’t push you back into debt while you’re paying it down.
Frequently asked questions
Is six months of expenses too much?
Not if your income is irregular or your household depends on one salary. For others, three months may be enough, with extra savings invested for the long term.
Should I invest my emergency fund?
No. Investments can fall in value just when you need the money. Keep it in cash, and invest money beyond your emergency fund.
Can my emergency fund be in a Cash ISA?
Yes, as long as it’s an easy-access account. From April 2027, under-65s will be able to pay up to £12,000 a year into Cash ISAs, which is still enough for most emergency funds.
Final thoughts
An emergency fund isn’t exciting, but it’s the most important money you’ll ever save. Work out your essential monthly spending, set a first milestone, automate a monthly transfer, and keep the money somewhere safe and accessible. Once it’s in place, you can invest with confidence.
This article is general information, not financial advice. Interest rates and protection limits can change; check with your provider and the FSCS.
by onchop.co.uk | Oct 25, 2026 | Business
Stocks and Shares ISA for Beginners
If you live in the UK and want to start investing, a Stocks and Shares ISA is usually the best place to begin. Any growth, dividends and interest inside it are free from UK income tax and capital gains tax, and you don’t even need to mention it on a tax return.
This guide explains how it works, what’s changing from April 2027, and how to make your first investment.
What is an ISA?
An Individual Savings Account (ISA) is a tax-free wrapper. It isn’t an investment in itself: it’s a container that protects what you put inside it from tax.
There are several types:
| ISA type | What it holds | Key point |
|---|
| Cash ISA | Cash savings | Interest is tax-free, no investment risk |
| Stocks and Shares ISA | Funds, ETFs, shares, bonds | Growth and dividends are tax-free; value can fall |
| Lifetime ISA | Cash or investments | For a first home or retirement, with a government bonus |
| Innovative Finance ISA | Peer-to-peer lending | Higher risk |
| Junior ISA | For children | Separate allowance |
The ISA allowance for 2026/27
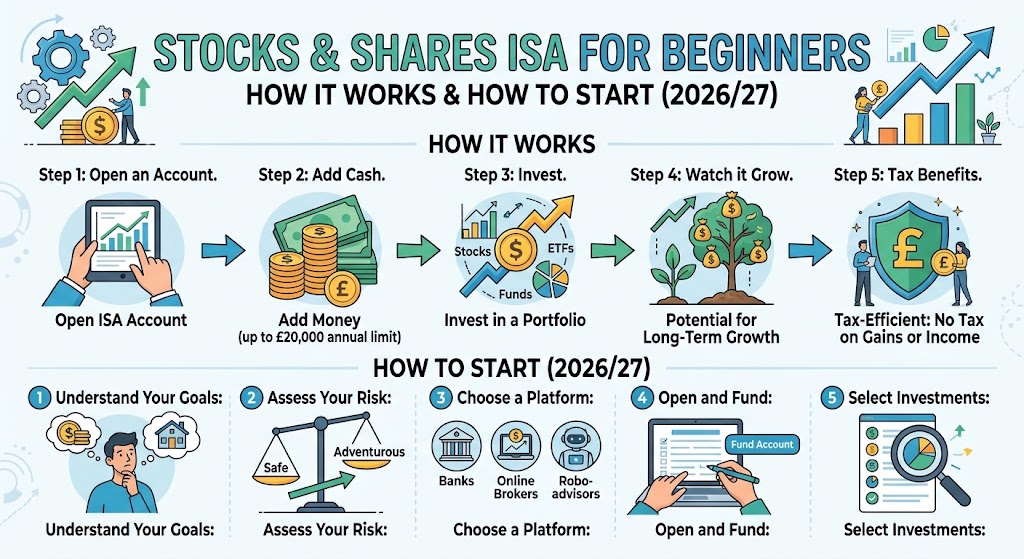
For the 2026/27 tax year (6 April 2026 to 5 April 2027), you can pay up to £20,000 into ISAs in total. You can split it across different ISA types in any way you like, and since April 2024 you can pay into more than one ISA of the same type in a tax year.
Two things to remember:
- The allowance doesn’t roll over. Anything unused by 5 April is lost.
- The Lifetime ISA limit of £4,000 a year sits inside the overall £20,000.
What’s changing from April 2027
The government has confirmed changes to Cash ISAs from 6 April 2027:
- If you’re under 65, you’ll be able to put a maximum of £12,000 a year into Cash ISAs.
- If you’re 65 or over, you can still put the full £20,000 into cash.
- The overall ISA allowance stays at £20,000, so under-65s will be able to put at least £8,000 into Stocks and Shares or other ISA types.
- Rules will also stop people getting round the limit, such as transfers from Stocks and Shares ISAs into Cash ISAs for under-65s.
Money already in your Cash ISA is not affected. And for 2026/27, you can still put the full £20,000 into a Cash ISA if you prefer.
The message from government is clear: it wants more savers to consider investing for the long term. Which makes it a good moment to understand Stocks and Shares ISAs.
Cash ISA or Stocks and Shares ISA?
| Cash ISA | Stocks and Shares ISA |
|---|
| Risk | Very low (eligible deposits protected by the FSCS) | Your investments can fall in value |
| Potential return | Interest rate offered | Historically higher over long periods, but not guaranteed |
| Best for | Emergency fund, goals within a few years | Goals five years away or more |
| Access | Easy, depending on the account | Usually easy, but you may sell at a loss in a downturn |
A common approach: keep your emergency fund in cash, and invest money you won’t need for at least five years.
How to choose a Stocks and Shares ISA provider
You open a Stocks and Shares ISA with an investment platform, a bank or a robo-adviser. Compare:
- Platform fees: a percentage of your pot, a flat monthly fee, or nothing at all. As a rough rule, percentage fees suit small pots and flat fees suit larger ones.
- Fund and trading charges: the ongoing charge of the funds you pick, plus any cost per trade.
- Investment choice: do they offer the low-cost global index funds or ETFs you want?
- Regular investing: can you set up automatic monthly payments, ideally with free regular purchases?
- Ready-made portfolios: useful if you’d rather not pick investments yourself.
- Ease of use and support: a clear app and a responsive help team matter more than you’d think.
- Regulation: check the provider is authorised by the Financial Conduct Authority.
To complete before publishing: add one or two providers with your affiliate links, checking fees and any welcome offers on the day you publish.
What should a beginner invest in?
Option 1: A global index fund or ETF
One fund that tracks a broad global index gives you a small slice of a large number of companies across many countries. It’s low cost, diversified and simple. For many beginners, it’s all they need.
Option 2: A ready-made portfolio
Many platforms offer portfolios matched to your attitude to risk (cautious, balanced, adventurous), rebalanced for you. Slightly more expensive than a single index fund, but completely hands-off.
What to avoid at first
- Picking individual shares with money you can’t afford to lose.
- Narrow themes that are in the headlines this week.
- Anything you can’t explain in one sentence.
How to start in 5 steps
- Build an emergency fund first, ideally three to six months of essential spending in cash.
- Open your Stocks and Shares ISA online. You’ll need your National Insurance number and bank details.
- Pay in: a lump sum, or a regular monthly amount. Even £25 or £50 a month is a meaningful start.
- Choose your investment, such as a global index fund or a ready-made portfolio.
- Leave it to grow, check in once or twice a year, and resist the urge to react to the news.
Mistakes to avoid
- Leaving money uninvested in cash inside your Stocks and Shares ISA for months.
- Paying high fees without realising.
- Selling in a panic when markets fall.
- Opening an ISA in the last days of the tax year in a rush.
- Withdrawing from a flexible ISA and assuming you can always put it back; check whether your ISA is flexible first.
Frequently asked questions
Can I lose money in a Stocks and Shares ISA?
Yes. The value of investments can go down as well as up, and you may get back less than you put in. That’s why it suits money you can leave invested for several years.
Can I have a Cash ISA and a Stocks and Shares ISA?
Yes, as long as your total payments across all ISAs stay within the £20,000 annual allowance. From April 2027, under-65s will be limited to £12,000 in cash within that total.
Can I transfer an old ISA?
Yes, you can transfer previous years’ ISA savings to another provider without losing the tax benefits. Always use the official transfer process rather than withdrawing the money yourself.
Do I need to declare my ISA to HMRC?
No. Income and gains inside an ISA are tax-free and don’t need to be reported on a tax return.
Final thoughts
A Stocks and Shares ISA is the simplest tax-free way for most people in the UK to start investing. Use your £20,000 allowance wisely, keep your emergency fund in cash, choose a low-cost diversified fund, and invest regularly. With the Cash ISA limit for under-65s falling to £12,000 from April 2027, now is a good time to understand your options.
This article is for general information only and isn’t financial advice. The value of investments can fall as well as rise. Tax rules depend on individual circumstances and may change.
by onchop.co.uk | Oct 24, 2026 | Good to Know
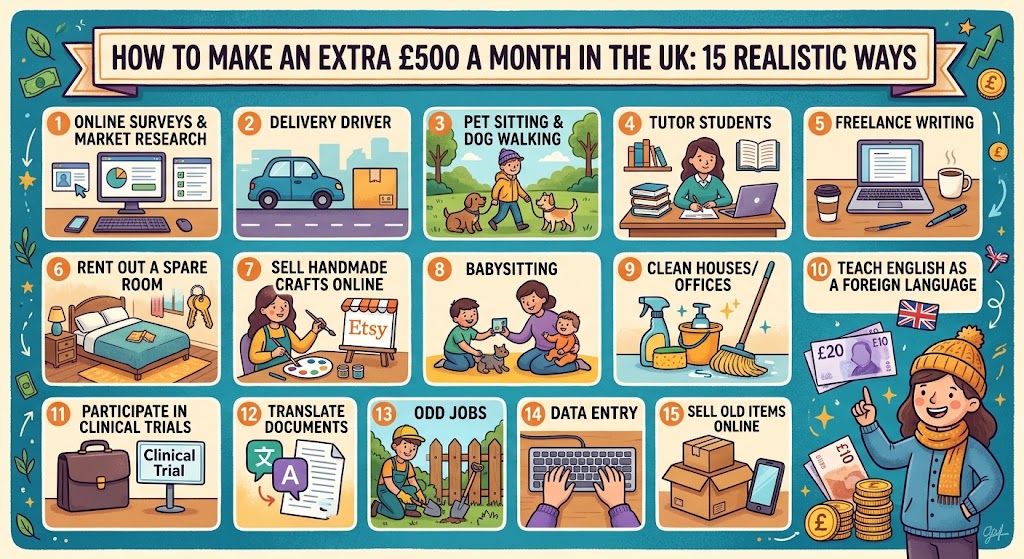
How to Make an Extra £500 a Month in the UK
£500 a month is £6,000 a year. That’s an emergency fund, a holiday, a big chunk of debt cleared, or the first step towards investing. It sounds like a lot, but for most people it’s reachable by combining two levers: spending less on things you don’t value, and earning a bit more from what you already have.
This guide shows you how to do both, with realistic numbers and no get-rich-quick nonsense.
Break £500 into smaller targets
£500 is intimidating as one number. Broken down, it looks very different:
- £125 a week
- about £17 a day
- or, for example: £150 saved on bills + £200 from a side hustle + £150 from selling things you no longer use
The trick is not to find one perfect idea, but to stack three or four small ones.
Part 1: Free up money you’re already spending (£50 to £200 a month)
This is often the fastest win, because it needs no new skills and no extra hours.
1. Audit your subscriptions
Streaming services, apps, gym memberships you don’t use, magazine subscriptions, premium versions of free tools. Go through your bank statements for the last three months and cancel what you wouldn’t sign up for again today.
2. Switch or haggle on your bills
Broadband, mobile and insurance providers often reward new customers more than loyal ones. When your contract ends, compare deals and call your provider before renewing. A SIM-only deal can be much cheaper than an expensive handset contract.
3. Check your energy tariff and usage
Compare tariffs regularly, take meter readings, and look for simple savings at home: draught-proofing, washing at lower temperatures, turning appliances off at the wall.
4. Plan your food shop
Meal planning, a shopping list, own-brand products and batch cooking can make a real difference to a household’s food bill, as can cutting back on takeaways and meal deals.
5. Check what you’re entitled to
Many people miss out on benefits, discounts or council tax reductions they qualify for. Use an independent benefits calculator to check, especially if your circumstances have changed recently.
Part 2: Quick cash from what you own (£100 to £300, often one-off)
6. Sell what you no longer use
Clothes, electronics, furniture, baby equipment, books and games. Online marketplaces and local selling groups make it easy. Good photos, honest descriptions and fair prices sell fastest.
7. Rent out your stuff or space
A driveway near a station or stadium, a garage for storage, tools or camera equipment you rarely use can all earn regular money through dedicated platforms.
8. Freelance your work skills
Writing, design, bookkeeping, admin, translation, video editing or web design can be sold to small businesses, either directly or through freelance platforms. Even five to eight hours a week at a fair hourly rate can get you most of the way to £500.
9. Tutoring
Subjects like maths, English and sciences are in steady demand, especially before exams. Online tutoring removes travel time.
10. Pet sitting and dog walking
Low startup costs and strong demand in most areas. Regular weekday walks for two or three dogs can add up quickly.
11. Cleaning, gardening and odd jobs
Reliable, well-reviewed help is hard to find. Local community groups and word of mouth are often the best marketing.
12. Rent out a spare room
The government’s Rent a Room scheme lets you earn a set amount tax-free each year from letting furnished accommodation in your own home. Check the current threshold and the rules (including your mortgage or tenancy agreement) on GOV.UK before you start.
13. Weekend or evening work
Hospitality, retail and events often need extra staff, especially around Christmas and summer. Less flexible than a side hustle, but reliable income.
14. Delivery and driving
Flexible, but calculate your real earnings after fuel, wear and insurance before committing.
15. Build something that grows
A blog, YouTube channel, newsletter or e-book won’t pay £500 next month. But over a year or two, it can become a lasting income stream. Do it alongside a faster option.
Three sample £500 plans
| Plan | Mix | Time per week |
|---|
| The saver | £150 cut from bills and subscriptions + £350 freelancing | 5 to 6 hours |
| The local hustler | £100 from bills + £250 dog walking + £150 selling items | 6 to 8 hours |
| The homeowner | Spare room under Rent a Room + £50 driveway rental | 1 to 2 hours |
These are illustrations: what you earn depends on your area, skills and the prices you set.
Don’t forget tax
- The £1,000 trading allowance: in the 2026/27 tax year, you can usually earn up to £1,000 in gross trading income without registering for Self Assessment. Above that, you’ll usually need to register by 5 October after the end of the tax year.
- £500 a month is £6,000 a year, well above the trading allowance. If most of it comes from self-employment, plan to register and keep simple records.
- Selling your own unwanted items is generally not trading.
- Rent a Room income has its own separate allowance.
Keep a simple spreadsheet of what you earn and spend from day one. Our guide to the best UK side hustles covers the tax rules in more detail.
Mistakes to avoid
- Chasing “passive income” schemes that cost money upfront and promise easy returns.
- Paying for courses before earning anything.
- Underpricing your time.
- Spending the extra money as soon as it arrives. Send it automatically to a separate savings account.
- Burning out by adding 20 hours of work on top of a full-time job.
Frequently asked questions
What is the fastest way to make £500?
Selling items you no longer use and cutting unused subscriptions and overpriced bills usually bring the quickest results.
Can I make £500 a month from home?
Yes, through freelancing, online tutoring, or a combination of savings and online selling.
It can, particularly with Universal Credit. Report your earnings and check how they affect your payments before you start.
Final thoughts
An extra £500 a month rarely comes from one big idea. It comes from stacking small, realistic wins: stop overpaying, sell what you don’t need, and pick one side hustle that fits your skills and schedule. Then put that money to work for your future.
General information only, not financial or tax advice. Thresholds and rules can change; check GOV.UK for your situation.
by onchop.co.uk | Oct 23, 2026 | Good to Know
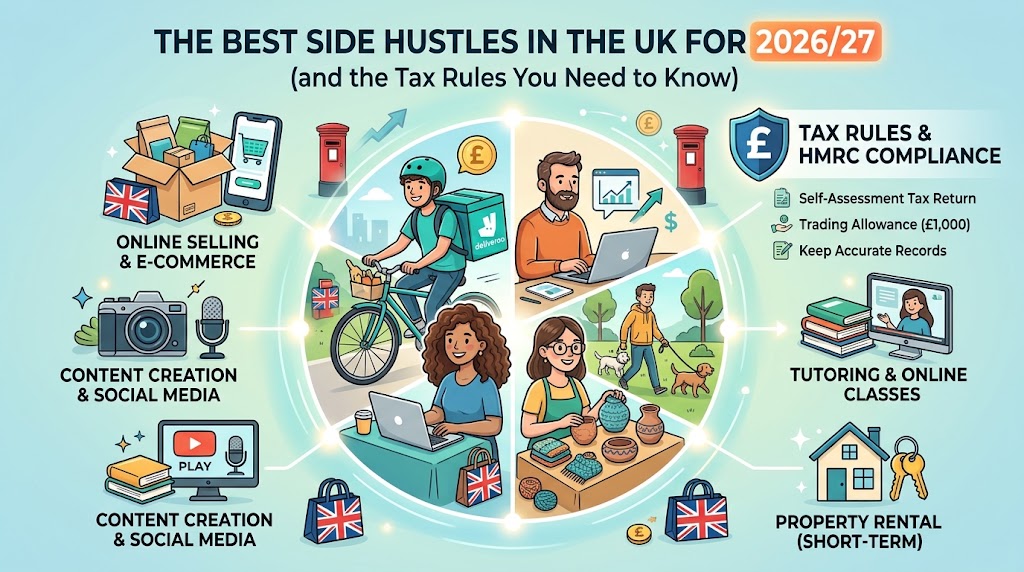
The Best Side Hustles in the UK for 2026/27
With bills still high and wages struggling to keep up, millions of people in the UK are looking for a way to earn a little extra. A side hustle can cover a monthly bill, build an emergency fund, or become the first step towards running your own business.
The trick is to pick something that fits your skills and your schedule, and to stay on the right side of HMRC from day one. This guide covers both.
How to choose the right side hustle
Before jumping into the latest idea from social media, ask yourself four questions:
- How many hours can I really give each week? Be honest. Five reliable hours beat twenty hours you never find.
- What can I already do? Your job, your hobbies and what friends ask you for help with are the fastest route to your first pound.
- Do I want to trade time for money, or build something that scales? Freelancing pays quickly; a blog or digital product takes longer but can earn while you sleep.
- How much can I invest upfront? Many good side hustles cost almost nothing to start.
12 side hustles that work in the UK
Selling online
1. Reselling clothes and items. Selling what you no longer need on platforms like Vinted or eBay is the easiest start. Some people move on to buying underpriced items at charity shops and car boot sales and reselling them.
2. Handmade products. Candles, jewellery, prints or personalised gifts can sell well on marketplaces such as Etsy, especially before Christmas.
3. Print on demand. You create designs, a partner company prints and ships t-shirts, mugs or posters only when someone orders. No stock, but margins per item are small.
Selling your skills
4. Freelancing. Writing, graphic design, video editing, bookkeeping, web design or virtual assistance can be offered on freelance platforms or directly to local businesses.
5. Online tutoring. If you are strong in maths, English, science or a language, tutoring pupils before GCSEs and A-levels is in steady demand, online or in person.
6. Social media management. Many small businesses know they should post regularly but have no time. Managing two or three accounts can bring a regular monthly income.
Local services
7. Pet sitting and dog walking. Low startup costs, flexible hours, and demand everywhere.
8. Cleaning, gardening and odd jobs. Reliable, well-reviewed local help is always sought after. Insurance is worth considering.
9. Delivery and driving. Food delivery and courier apps offer flexibility, but factor in fuel, wear on your vehicle and insurance before calculating what you really earn.
Using what you own
10. Renting a spare room. The government’s Rent a Room scheme lets you earn a set amount tax-free from furnished accommodation in your own home. Check the current threshold on GOV.UK.
11. Renting out a parking space or storage. If you live near a station, stadium or city centre, a driveway can earn money with very little effort.
Building something long-term
12. Blogging, YouTube or self-publishing. A blog with affiliate links, a YouTube channel, or an e-book on Amazon KDP takes months to grow, but can turn into a lasting source of income. It suits people who enjoy writing, teaching or creating.
| Side hustle | Startup cost | Time to first income | Scales? |
|---|
| Reselling | Very low | Days | Limited |
| Freelancing | Very low | Weeks | Medium |
| Tutoring | Very low | Weeks | Limited |
| Pet sitting | Very low | Weeks | Limited |
| Handmade products | Low to medium | Weeks | Medium |
| Blog, YouTube, e-books | Low | Months | High |
Side hustle tax: what HMRC expects in 2026/27
The 2026/27 tax year runs from 6 April 2026 to 5 April 2027. Here are the rules that matter most.
The £1,000 trading allowance
Every individual gets a £1,000 trading allowance per tax year. If your gross income from trading (before expenses) is £1,000 or less, you usually don’t need to register for Self Assessment or pay tax on it.
Two details people often miss:
- It’s per person, not per side hustle. If you sell on Vinted, walk dogs and do some freelance design, all that income is added together against the same £1,000.
- It’s based on income, not profit. £1,200 of sales with £500 of costs is still above the threshold.
Above £1,000: register for Self Assessment
If your gross trading income goes over £1,000 in a tax year, you usually need to register for Self Assessment by 5 October following the end of that tax year, then file your return and pay any tax by 31 January.
You can then choose between deducting the £1,000 allowance or your actual expenses, whichever is better for you. Your profit is added to your other income and taxed at your marginal rate. The personal allowance remains £12,570 for 2026/27.
Selling your own unwanted things
Clearing out your wardrobe or loft is generally not trading. HMRC looks at whether you are buying to resell, making items to sell, or otherwise trading with a view to profit.
Online marketplaces and gig platforms are required to share information about sellers’ income with HMRC once certain thresholds are met. This didn’t create a new tax, but it means HMRC can more easily match platform income against tax returns. Keeping simple records from the start avoids unpleasant letters later.
Making Tax Digital
From April 2026, Making Tax Digital for Income Tax applies to people whose gross business or property income is over £50,000. Most side hustlers are well below this, but it’s worth knowing as you grow.
Getting started: a 7-day plan
- Day 1: List your skills, possessions you could sell or rent, and the hours you have each week.
- Day 2: Pick one side hustle from the list above. Just one.
- Day 3: Look at what others charge and decide your price.
- Day 4: Create your profile, listing or simple one-page website.
- Day 5: Tell friends, family and local groups what you offer.
- Day 6: Set up a basic spreadsheet to track income and expenses.
- Day 7: Deliver your first job or list your first items, then review what worked.
Mistakes to avoid
- Paying for “get rich quick” courses before earning your first pound.
- Ignoring tax until HMRC writes to you.
- Underpricing your time and ending up exhausted for very little.
- Spreading yourself across five ideas at once.
- Breaking your employment contract: check it for clauses about outside work.
Frequently asked questions
Will my employer find out about my side hustle?
Self Assessment is between you and HMRC. However, your contract may require you to declare outside work, so check it first.
Do I need to set up a limited company?
No. Most side hustlers start as sole traders. A limited company may make sense later, once profits are significant; an accountant can advise.
Can I have a side hustle while on Universal Credit?
Yes, but you must report your earnings, and they can affect your payment. Check the rules on GOV.UK before starting.
Final thoughts
The best side hustle is the one you’ll actually stick with: something that fits your skills, your schedule and your goals. Start small, keep records from day one, and keep an eye on the £1,000 trading allowance.
If you’d like to build a side business on deeper foundations, Entrepreneurship with “I AM” combines faith and strategy in 14 chapters, with a practical 30-day action plan.
This article is general information, not tax advice. Rules and thresholds can change; check GOV.UK or speak to an accountant about your situation.