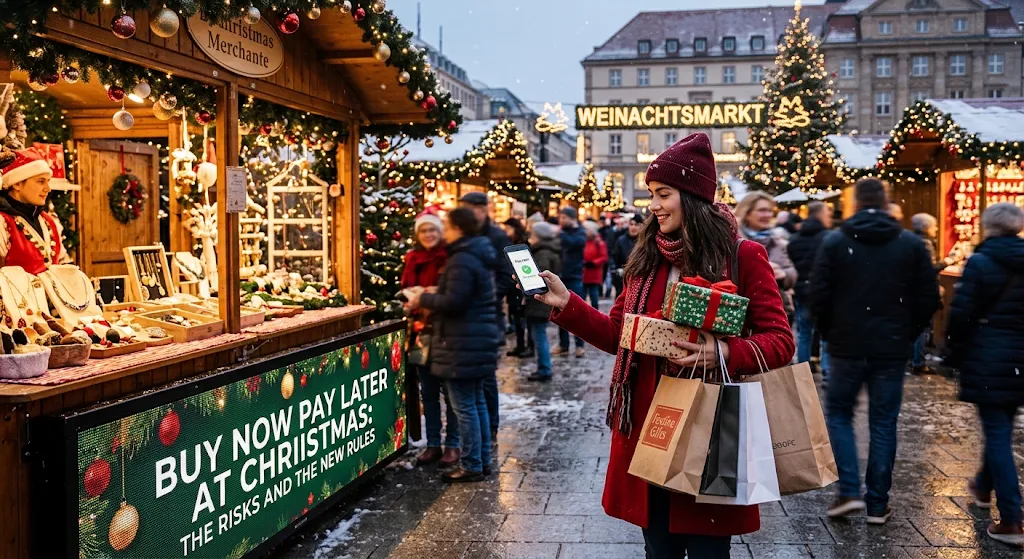
Spread the cost of Christmas over three easy payments, interest-free. At the checkout, Buy Now Pay Later (BNPL) feels like a little gift to yourself. In January, when several instalments land in the same week as the energy bill, it can feel very different.
This Christmas is the first festive season under the new buy now pay later rules in the UK. Since 15 July 2026, most BNPL agreements are regulated by the Financial Conduct Authority (FCA). That brings real protections, but it does not make BNPL risk-free. In this guide, we explain what has changed, what is still not covered, and how to use BNPL at Christmas without starting 2027 in debt.
Buy Now Pay Later rules UK: the summary
Click on a protection to jump straight to the detailed section.
| Protection | What it means for you | Who it covers | Date key |
|---|---|---|---|
| Before you buy Affordability checks | The lender must check you can afford the repayments before lending | Regulated BNPL agreements | Agreements from 15/07/2026 |
| Before you buy Clear information | Amount borrowed, repayment dates and amounts, late fee and your rights shown up front | Regulated BNPL agreements | Agreements from 15/07/2026 |
| If you struggle Support with missed payments | The lender must contact you, explain the consequences and offer support | Regulated BNPL agreements | January instalments: plan now |
| If something goes wrong Section 75 refunds | You may claim a refund from the lender if the goods are faulty or never arrive | Regulated BNPL agreements | Agreements from 15/07/2026 |
| Complaints Financial Ombudsman Service | Free, independent complaint route if the lender doesn’t resolve your issue | Regulated BNPL agreements | After the lender’s final response |
| Not covered Exempt deals | No new protections | Agreements before 15/07/2026, and BNPL offered by the retailer itself | Check before you click “pay” |
What changed on 15 July 2026?
Until this summer, the most common form of BNPL in the UK was unregulated. Lenders did not have to check whether you could afford to repay, and you had limited options if something went wrong.
Since 15 July 2026, the FCA regulates what it calls Deferred Payment Credit (DPC): interest-free credit that you repay in 12 or fewer instalments, over 12 months or less. This is the classic “pay in 3” or “pay in 30 days” option you see at online checkouts.
The rules apply when the lender is a different business from the retailer selling you the goods, which is the case for the big third-party BNPL providers. Firms that were already lending can keep operating under the FCA’s temporary permissions regime while their full authorisation is processed, but they must follow the FCA rules for agreements made from 15 July.
The new protections, one by one
Affordability checks
Before you take out a regulated BNPL agreement, the lender must check that you can afford to repay. In practice, this may mean more detailed checks than before, possibly including a look at your credit file. If a lender refuses, take it as useful information rather than a challenge to find another provider.
Clear information before you agree
The lender must tell you, before you sign up:
- how much you are borrowing;
- when each repayment is due and how much it will be;
- the amount of any late fee;
- your rights and protections.
Take ten seconds to read this screen. It is the moment to spot a repayment that falls on the wrong day of the month.
Support if you miss a payment
If you miss a repayment, the lender must contact you and explain what it means. If you are struggling, the lender must offer support, for example by discussing a new repayment plan. You can also get free, impartial debt guidance from MoneyHelper, the government-backed service.
Section 75 refunds
If something you bought with regulated BNPL is faulty, not as described or never arrives, you may be able to claim a refund from the lender under Section 75 of the Consumer Credit Act, the same protection you get with a credit card. Section 75 generally applies to single items priced over £100 and up to £30,000, so check the details of your purchase.
Complaints to the Financial Ombudsman
If you have a problem, complain to the lender first. If you are not happy with its answer, you can take your complaint to the Financial Ombudsman Service, free of charge.
What the new rules don’t cover
The new regime is a big step forward, but two gaps matter at Christmas:
- Agreements taken out before 15 July 2026 stay unregulated, even if you are still repaying them.
- BNPL offered directly by the retailer (where the shop itself lends you the money) is not covered by the DPC rules.
Also remember that some products marketed as “pay later” actually charge interest. These are different credit products with their own rules, and they can be much more expensive. To check a lender, use the FCA Firm Checker and look for an authorised firm, or one on the temporary permissions list.
The real risks of BNPL at Christmas
BNPL is popular at Christmas. According to YouGov, nearly one in five UK adults (19%) borrowed or used credit for Christmas spending in 2025, and 29% of those borrowers used BNPL services. Regulation doesn’t change the main dangers.
Stacking several plans at once
One “pay in 3” plan is easy to follow. Five plans with different providers, all started in December, can add up to a large monthly bill in January and February. Each lender sees only part of the picture.
The January squeeze
December pay often arrives early, which makes January a long month. BNPL instalments then compete with rent, council tax and energy bills. This is when missed payments happen.
Late fees and your credit file
Late fees vary between providers and must be shown before you agree. Some providers, including Klarna, report BNPL use and missed payments to credit reference agencies, so a missed instalment can affect your ability to borrow later. Read our guide on How to Check and Improve Your Credit Score in the UK to understand what lenders see.
Spending more than planned
Splitting a price into smaller chunks makes it feel cheaper. It isn’t. A £120 gift paid in three instalments still costs £120, and it is easy to add items you would not have bought outright.
How to use BNPL safely this Christmas
- Set a Christmas budget first, then decide whether BNPL fits within it, not the other way round.
- Limit yourself to one or two plans at a time, and keep a simple list of every instalment and its date.
- Match repayment dates to payday, especially in January.
- Check the lender is regulated and the agreement is with a third-party lender, so the new protections apply.
- Turn on payment reminders in the provider’s app.
- Ask for help early if you think you will miss a payment: contact the lender before the due date, and speak to MoneyHelper if needed.
FAQ: Buy Now Pay Later rules UK
Is Buy Now Pay Later regulated in the UK now?
Yes, for most deals. Since 15 July 2026, interest-free BNPL repaid in 12 or fewer instalments within 12 months is regulated by the FCA when the lender is separate from the retailer. Agreements taken out before that date are not covered.
Will using BNPL affect my credit score?
It can. Lenders may check your credit file as part of affordability checks, and some providers report your BNPL use and any missed payments to credit reference agencies. Paying on time helps; missing payments can harm your score.
Can I get my money back if a Christmas present never arrives?
Contact the retailer first. If that fails and you used regulated BNPL, you may be able to claim from the lender under Section 75 of the Consumer Credit Act, as with a credit card, provided the purchase meets the Section 75 conditions.
Are there limits on BNPL late fees?
The FCA rules require lenders to tell you the late fee before you agree. Check the amount on the agreement screen and in your provider’s terms, as it varies between companies.
What should I do if I can’t keep up with BNPL payments?
Contact your lender as soon as possible: under the new rules, it must offer support if you are struggling. You can also get free, confidential debt advice from MoneyHelper.
Conclusion: enjoy Christmas, protect your January
The new buy now pay later rules in the UK make BNPL safer than it was a year ago: affordability checks, clear information, Section 75 protection and access to the Financial Ombudsman. But the biggest protection is still your own plan. Set a budget, keep BNPL to a minimum, and check each lender before you click “pay”.
Want to build a little cushion for next Christmas instead of borrowing? Compare easy-access savings accounts and start putting a small amount aside each month: [AFFILIATE LINK TO ADD]
Sources: FCA (Buy Now Pay Later consumer guidance and press release on new protections for BNPL borrowers), YouGov (Christmas borrowing survey, 12 January 2026), checkmyfile (BNPL rules explained), Which? (Klarna credit reporting). Information checked on 15 November 2026; rules can change, so check the FCA website before making financial decisions. This article is general information, not financial advice.
0 Comments