Lifetime ISA vs Stocks and Shares ISA
If you’re saving for your first home or for retirement, you’ve probably come across two very different ISAs: the Lifetime ISA, with its generous government bonus, and the more flexible Stocks and Shares ISA. Both can grow your money tax-free. But choosing the wrong one for your goal can cost you, sometimes literally, through a withdrawal penalty.
This guide explains how each works, who they suit, and how many savers combine the two.
This article is general information, not financial advice. Rules and figures change: check gov.uk before you act, and consider speaking to a regulated adviser for your own situation.
The basics: your ISA allowance
Every UK adult resident can put up to £20,000 a year into ISAs, split across cash ISAs, Stocks and Shares ISAs, Innovative Finance ISAs and Lifetime ISAs. Money inside an ISA grows free of income tax and capital gains tax.
A previously announced plan to cut the cash ISA limit to £12,000 for under-65s from April 2027 has been reported as dropped; check the latest position on gov.uk before you plan around it.
How the Lifetime ISA works
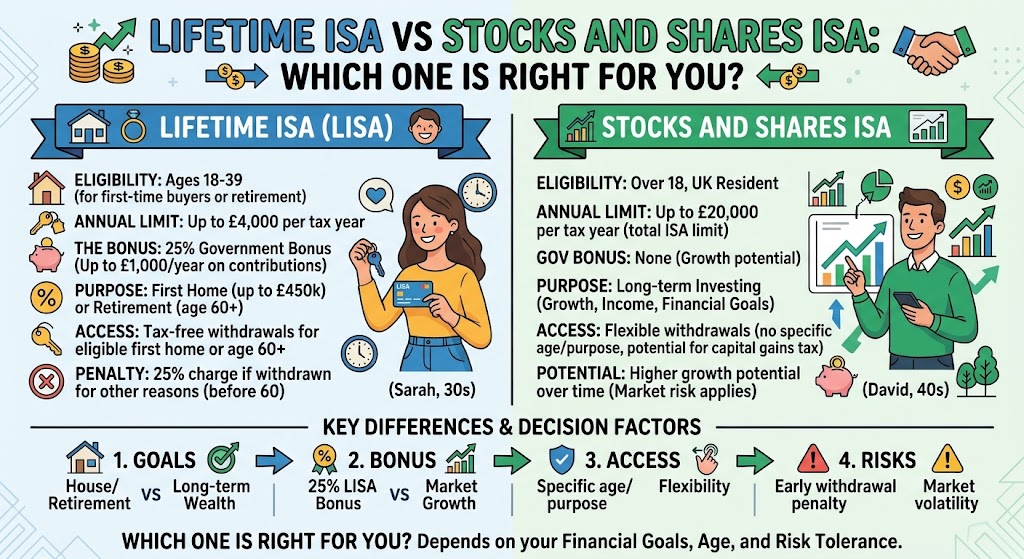
- Who can open one: you must be aged 18 to 39.
- How much: up to £4,000 a year, which counts towards your £20,000 allowance.
- The bonus: the government adds 25% of what you pay in, up to £1,000 a year.
- How long: you can keep paying in and receiving the bonus until the day before you turn 50.
- Cash or investments: Lifetime ISAs come in both cash and stocks and shares versions.
You can withdraw without penalty in three cases:
- To buy your first home, costing £450,000 or less, using a mortgage, through a conveyancer.
- From age 60, for any purpose.
- If you’re terminally ill with less than 12 months to live.
Any other withdrawal triggers a 25% charge on the amount you take out. Because the charge applies to your money plus the bonus, you end up with less than you put in: withdraw £1,000 (£800 of your money plus £200 bonus) and you get back £750.
Coming change: the government has announced plans to replace the Lifetime ISA with a new ISA focused solely on first-time buyers, from April 2029. Details may still evolve; existing accounts and the rules for them should be confirmed on gov.uk.
How the Stocks and Shares ISA works
- Who: any UK resident aged 18 or over.
- How much: up to your full £20,000 allowance.
- Investments: funds, index trackers, ETFs, shares, bonds.
- Access: you can withdraw at any time, with no government penalty (though the value of your investments can go down as well as up).
- No bonus, but complete flexibility.
We covered the details in our guide to Stocks and Shares ISAs for beginners.
Side-by-side comparison
| Lifetime ISA | Stocks and Shares ISA | |
|---|---|---|
| Age to open | 18–39 | 18+ |
| Annual limit | £4,000 | Up to £20,000 |
| Government bonus | 25% (up to £1,000 a year) | None |
| Access | First home, age 60+, terminal illness; otherwise 25% charge | Any time |
| Best for | First home under £450,000, or retirement top-up | Flexible medium- to long-term investing |
Which one should you choose?
Choose the Lifetime ISA first if:
- you’re 18–39 and plan to buy your first home, and it’s likely to cost £450,000 or less;
- you’re confident you won’t need the money before then.
In high-price areas, check the £450,000 cap carefully: if your target home costs more, the penalty applies.
Choose the Stocks and Shares ISA first if:
- you want flexibility to access your money;
- you already own a home, or you’re over 39;
- you’re investing for goals other than a first home.
Using both: many savers put £4,000 a year into a Lifetime ISA for the bonus and invest the rest of their allowance in a Stocks and Shares ISA for flexibility.
Lifetime ISA or pension for retirement?
For most employees, a workplace pension is a better first step for retirement savings, because your employer contributes too. Opting out of a workplace pension to fund a Lifetime ISA usually means losing your employer’s contributions. Our guide to pensions for beginners explains why.
Mistakes to avoid
- Using a Lifetime ISA as an emergency fund: the 25% charge makes it an expensive place for money you may need.
- Forgetting the £450,000 cap.
- Opening a Lifetime ISA too late to use it: there are rules on how long the account must be open before a first-home withdrawal.
- Going over your £20,000 total allowance across all ISAs.
FAQ
Can I have a Lifetime ISA and a Help to Buy ISA? You can hold both, but you can only use the government bonus from one of them towards the purchase of your first home.
Can I open a new ISA of the same type each year? Recent rule changes allow you to pay into more than one ISA of the same type in a tax year, within the overall £20,000. Lifetime ISAs remain limited to one subscription per year.
Conclusion
The Lifetime ISA is hard to beat for first-time buyers aged 18–39 thanks to its 25% bonus, as long as you’re sure about the purpose. The Stocks and Shares ISA offers flexibility for everything else. If in doubt, combine the two, and always build an emergency fund first.
0 Comments